Insights · Cross-Chain
How Cross-Chain Bridges Complicate Cryptocurrency Tracing
Bridges break the single-ledger trail. Tracing across them requires matching protocol events, amounts and timing on both networks.
Why value moves between blockchains
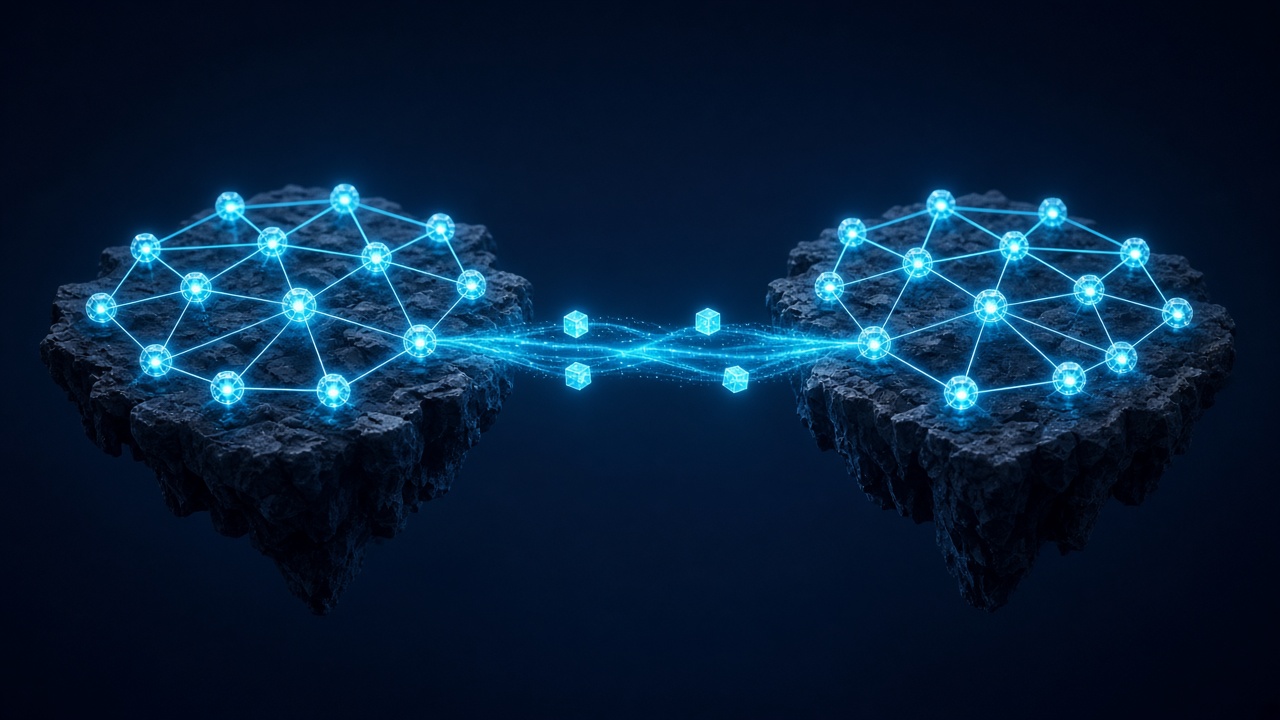
Blockchains are separate ledgers. Assets native to one network cannot appear on another without a mechanism that moves or represents value across the boundary. Users move funds between networks to reach different applications, lower fees or new markets, and people trying to obscure a money trail do the same. Cross-chain movement is therefore common in both legitimate activity and in the layering stage of fraud.
How a bridge transfer works
Most bridges follow one of a few designs. In a lock and mint design, tokens are deposited into a contract on the source chain and a wrapped representation is minted on the destination chain. In a burn and release design, the wrapped asset is destroyed when the original is redeemed. Liquidity-based designs work differently: the user deposits into a pool on one network and is paid out from a pool on the other, so no single transaction ever carries the same coins across. In every design, the transfer produces two or more events on two or more independent ledgers.
Where the trail breaks
Each network records only its own part of the transfer. The source chain shows a deposit into a bridge contract. The destination chain shows a release from a bridge contract or a liquidity pool. Neither ledger, viewed alone, proves that the two events belong to the same transfer. The transaction hashes differ, the addresses may differ, and with pooled designs the paid-out funds are not even the same units that were deposited. A single-ledger explorer simply runs out of trail at the bridge boundary.
What can reconnect the trail
Tracing across a bridge relies on correlation rather than direct linkage.
- Protocol events. Many bridges emit structured events and message identifiers that reference the corresponding transaction on the other network. Where these exist, the connection can be established with high confidence.
- Amounts. The value released on the destination side is often the deposited amount minus a predictable fee, which narrows the candidate set.
- Timing. Destination releases usually occur within a protocol-typical window after the deposit.
- Addresses. Some designs pay out to the same address string on the destination network, which is a strong supporting signal.
Evidence strength varies by link
Not every reconnection carries the same weight. A protocol message that explicitly references both transactions is close to verification. A candidate match based on amount and timing alone is a hypothesis that must be tested against alternatives, because similar amounts move constantly. In our own investigations, each cross-chain link is classified as verified, protocol-supported, probable or unresolved, and only links that survive analyst review appear in a report. Similar amounts and timestamps can suggest a relationship; they do not independently prove that the same funds moved.
Practical limits
- Some bridges and aggregators route through several networks in one user action, multiplying the number of ledgers to query.
- Privacy-enhancing protocols and mixers deliberately break amount and timing correlation.
- Centralized exchanges can act as informal bridges: a deposit on one network and a withdrawal on another leaves no on-chain link at all, and only the exchange's own records can reconnect it.
- Indexing gaps and incomplete data can hide candidate transactions even where the trail exists.
What this means for an investigation
Cross-chain movement adds work, not impossibility. The important consequence is timing: bridge events, exchange records and platform logs are easier to obtain and corroborate while they are fresh. If funds crossed networks, preserve every transaction hash and address you hold from each chain, and note the networks involved. The more complete the starting set, the more of the path can be reconstructed.
This article explains general concepts and does not constitute legal or investment advice. Cases involving multiple networks can be reviewed through our confidential case intake.